Yes, you can get a Golden Visa with mortgaged property in the UAE. In Dubai, the qualifying property or combined properties must have a total value of at least AED 2 million, and a mortgage does not automatically disqualify you. The application depends on the property records and mortgage documents supporting your case.
It’s understandable to wonder whether you must pay off a large part of the loan before applying. The key is to distinguish the property’s qualifying value from the evidence needed to document ownership and financing. This guide explains how mortgaged and off-plan properties are assessed, whether multiple properties may count toward the threshold, and which title, valuation and lender documents may be required.
You’ll also learn how to prepare for an application and what to consider when maintaining eligibility for renewal. Understanding the requirements can help you assess your property position before deciding what to do next.
Key Takeaways
- Assess whether your property or eligible properties meet Dubai’s AED 2 million value threshold and understand how a mortgage affects the application.
- Prepare the title deed and mortgage-related records that help document ownership, property value, and the outstanding balance.
- Learn when multiple properties or shared ownership may count toward the threshold, and what evidence supports your share.
- Understand how title deed details and market valuation can affect eligibility, then plan ahead for renewal requirements.
- Use the property criteria to guide your next investment decision, whether you are considering a ready home or an off-plan purchase.
Can I obtain a Golden Visa with a mortgaged property in Dubai?
Yes. You can get a UAE Golden Visa with mortgaged property if the property meets the qualifying value and ownership requirements and you provide the required financing evidence. The key considerations are the property’s qualifying value and the mortgage documentation, not simply whether a loan exists.
The property route is governed by Article 8 of the Annex to Cabinet Resolution No. 65 of 2022. The application process relies on official land department property records and valuation frameworks; different regions may have specific application procedures and property documentation.
-
Confirm property investor eligibility
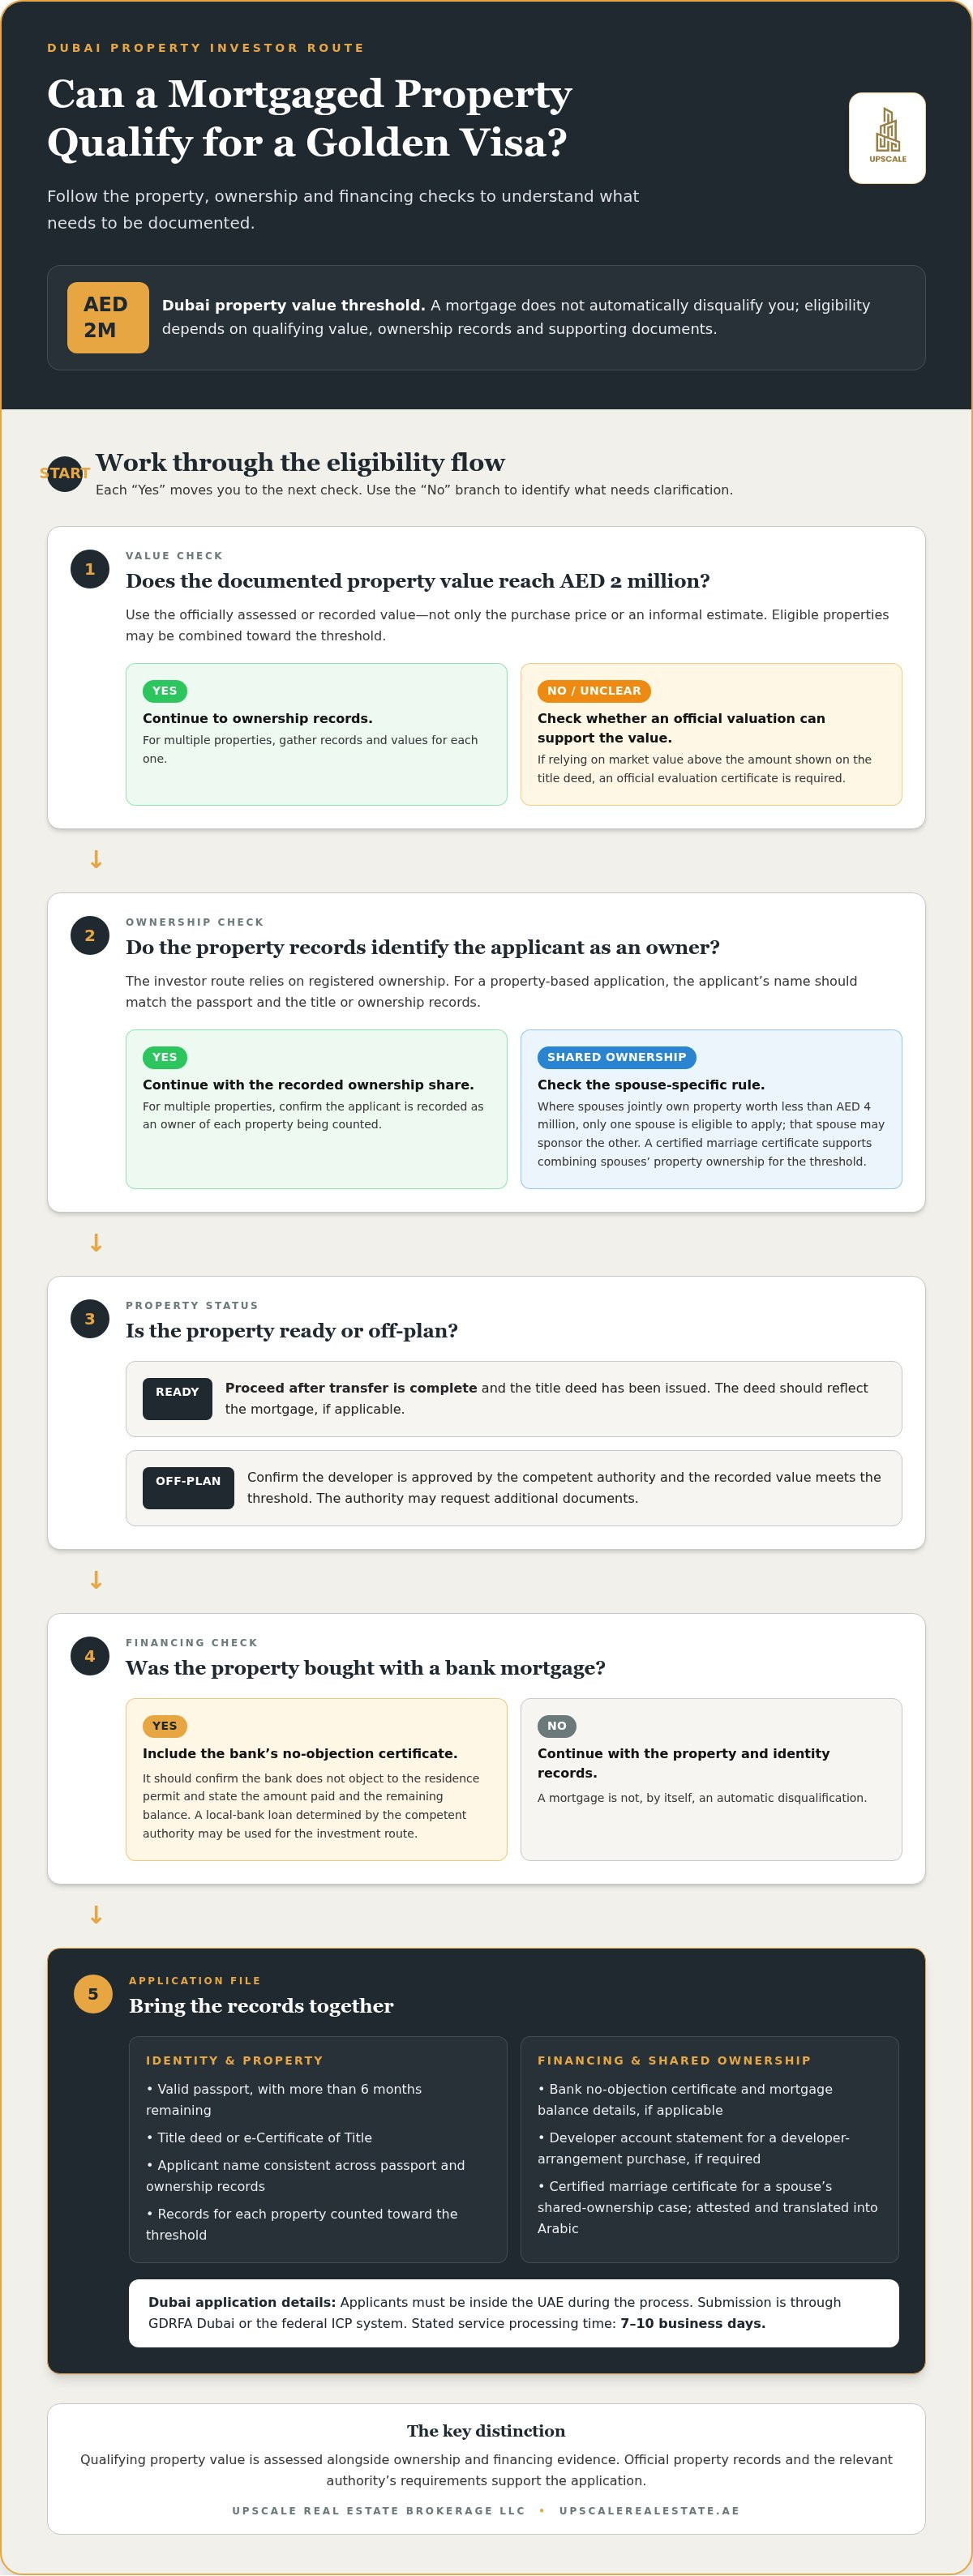
Start by checking that the property or qualifying properties are registered in your name and meet the AED 2 million threshold. The investor route requires the qualifying property to be wholly owned by the applicant, either as one property or across several. Compare the officially assessed value with the threshold, rather than relying only on the purchase price or an informal estimate.
-
Verify mortgaged-property eligibility
Gather mortgage evidence before preparing your residence application. For a property bought with a bank mortgage, the bank’s no-objection certificate should confirm that it does not object to the residence permit and state the amount paid and the remaining balance. A loan from a local bank determined by the competent authority may be used for the investment route.
- First, establish whether the property is ready or off-plan. A ready property can be considered after the transfer is complete and the title deed showing the mortgage has been issued. For off-plan real estate, confirm that the developer is approved by the competent authority and that the recorded value meets the threshold. The relevant authority may request additional documents before approving an application.
- Check how the property value and ownership are documented. The title deed must show a value of at least AED 2 million for the application. If the application relies on market value above the amount shown on the deed, an official evaluation certificate is required. Owners should also ensure that the applicant’s name matches the passport and that mortgage records clearly identify the property.
- Separate your eligibility from a spouse’s application. Shared ownership does not automatically let each spouse count the full property value. Where spouses jointly own a property worth less than AED 4 million, only one spouse is eligible to apply, and that spouse may sponsor the other. A certified marriage certificate supports combining spouses’ property ownership for the threshold.
What are the required documents needed for a 10-year investor Visa in the UAE?
Prepare the property and identity records before submitting a Dubai investor Golden Visa application. The documents should establish who is applying, which property supports the application, and how any mortgage or shared ownership is recorded.
- Prepare a valid passport and plan to apply from inside the UAE. Dubai property investor applicants must be in the country, and the passport must remain valid for more than 6 months. Check that the applicant’s name matches the property ownership record; a mismatch can complicate the link between identity and investment.
- Collect the property’s title deed or e-Certificate of Title. These records identify the registered owner and property details used in the application. For a ready property, apply after the transfer is complete and the title deed reflects the mortgage, if applicable. Make sure the document is legible and the applicant’s name matches the passport.
- Add mortgage evidence if a bank financed the purchase. A bank no-objection certificate should state that the bank does not object to issuing the residence permit and show the amount paid and remaining balance. For a property purchased through a developer arrangement, include the developer account statement required for the residence application.
- Organize supporting records if multiple properties or a spouse’s application are involved. If several properties contribute to eligibility, prepare the title or ownership record for each so the registered owners and values can be reviewed together. Spouses applying through shared ownership should provide a certified marriage certificate, attested and translated into Arabic.
- Submit through GDRFA Dubai or the federal ICP system. Applicants must be inside the UAE during the Dubai application process. The stated service processing time is 7-10 business days; keep the submitted passport, title deed, mortgage evidence, and any marriage certificate consistent across the application. For property planning before purchase, explore Dubai property ownership options alongside the document requirements.
Combining multiple properties to meet the threshold
Dubai allows an investor to combine eligible property values toward the AED 2 million Golden Visa threshold. The decisive details are each property’s recorded value, registered ownership, and the applicant’s share.
- List every eligible property registered in your name. Dubai’s property investor route allows several properties to count together, rather than requiring one property worth AED 2 million. Use documented property values, not estimates, when calculating the combined amount.
- Match each property value to its ownership record. Gather the title deed or e-Certificate of Title for every property included. Confirm that the applicant is recorded as an owner and that the documents clearly identify each unit. A property registered only to someone else cannot simply be added to your personal total.
- Calculate your share before relying on jointly owned real estate. For shared ownership, the applicant’s own share must be worth at least AED 2 million. That individual share alone falls below the threshold.
- For spouses combining ownership, prepare a certified marriage certificate with the property records. Spouses may combine their ownership to meet the threshold when they provide this document. However, when spouses jointly own property worth less than AED 4 million, only one spouse is eligible to apply; that applicant may sponsor the other. Don’t assume both spouses qualify independently from the same property.
- Check the mortgage records and value evidence for every property included. A mortgage does not automatically prevent a property from counting, but the application must document ownership and the relevant property value. Keep the bank’s NOC or other mortgage evidence with the title records so the amount paid and outstanding balance are clear. This also helps distinguish the property’s total value from the applicant’s ownership share.
- Reconcile the total before submitting the application. Add the qualifying values, check the ownership shares, and organize the supporting documents in the same order. The threshold concerns property value, not the combined purchase price or loan amount. If approved, the property investor Golden Visa provides 10 years of residence; applicants must also maintain comprehensive health insurance for themselves and family members, as required by the competent local authority.
Title deed and market valuation requirements
Use the title deed, valuation record and mortgage documents to show ownership and qualifying value. For a Dubai application, ensure the records present a consistent picture of the property and applicant.
-
Obtain the bank no-objection certificate
Ask the financing bank for a no-objection certificate supporting the residence permit application. The letter should state that the bank does not object and show the amount paid and remaining balance. Compare those figures with your loan statement before submitting. If either amount is missing, the application may not clearly establish the mortgage position.
-
Compile mortgage and ownership documents
Review the title deed or e-Certificate of Title alongside the bank’s NOC and mortgage statement. Check that the applicant’s name matches the passport and property ownership record. If multiple properties are involved, include ownership documents for each. Keep the records together so the application clearly connects the owner, property, bank financing, amount paid and outstanding balance.
- Confirm the value recorded on the Dubai title deed. The deed must state a property value of at least AED 2 million for the application. Use the DLD-recorded value as the reference point when assessing eligibility. A purchase price, online estimate, or personal valuation does not replace the figure on the official ownership record.
- Arrange an official evaluation certificate if relying on market value above the deed amount. Dubai title deed owners may apply when the property’s market value exceeds AED 2 million, with an official evaluation certificate. Keep this certificate distinct from a sales listing or an informal appraisal. The valuation evidence should support the amount used in the Golden Residence application.
- Check the source of mortgage financing before applying. For the UAE real estate investor route, a loan must come from a local bank determined by the competent local authority and a UAE-licensed bank. Keep the lender details consistent across the bank letter, loan records and property documents.
- Review the title deed and mortgage letter as one evidence set. Confirm that the property identifier, registered owner and financing details correspond across the documents. If a sponsor is involved in the wider residence application, keep that person’s identity records separate from the property owner’s evidence. Clear records help distinguish sponsorship from property ownership during the application for term residency.
Golden Visa duration and renewal
Dubai’s property investor Golden Residence Permit is valid for 10 years and is renewable. A property transaction or change in financing can affect the ownership evidence behind the route, so plan around the property record as well as the permit expiry.
- Record your permit’s expiry date and prepare for renewal in advance. Treat renewal as a fresh review of your qualifying investment evidence, and keep property ownership records and mortgage documents organized throughout your residency.
- Keep the qualifying property and ownership position aligned with the basis for your visa. Keep the property and ownership documentation in order throughout the residence permit’s validity. A sale or ownership transfer is therefore different from refinancing: a transfer changes the registered owner and may affect the investment basis supporting the permit.
- If you refinance, retain the updated loan and bank records alongside the title deed. Refinancing changes the financing details, while the registered owner may remain unchanged. The key question is whether the qualifying property and ownership continue to meet the residence conditions. Keep the replacement lender’s documents consistent with the property records for any later review.
- Consider the consequences before selling or transferring a qualifying property. A sale changes ownership, and the Golden Residence route requires continuity of ownership during the permit’s validity. If other eligible properties remain registered to you, their combined qualifying value may support the threshold. Your ownership and value records must still demonstrate eligibility.
- Plan family sponsorship and portfolio decisions with the 10-year term in view. A Dubai property investor visa holder may sponsor a spouse and children for 10 years. Keep their residence records and required health insurance coordinated with the principal applicant’s plans. A property purchase for residency is also a separate decision from citizenship planning.
- Account for emirate-specific conditions if your investment is outside Dubai. Abu Dhabi property applicants must keep the property for at least 2 years after the Golden Visa is issued. That requirement differs from Dubai’s 10-year permit framework, so align property decisions with the emirate and route tied to your application. For long-term property oversight, explore property portfolio support.
Upscale Real Estate Brokerage: Ready Property Sales
Upscale Real Estate Brokerage LLC offers Ready Property Sales for buyers assessing Dubai homes as part of an investment strategy. If you’re comparing ready properties, consider how ownership records, property value and mortgage documents may relate to your Golden Visa plans before purchasing.
If you’re weighing a completed home against a future development, the brokerage also offers Off-Plan Project Sales. Residential Leasing and Property Management can support owners’ broader property plans after purchase. These services connect investment decisions with practical ownership and leasing considerations, while visa eligibility remains subject to the applicable property and residency requirements.
For a discussion about ready properties in Dubai, contact Upscale Real Estate Brokerage LLC.
Make Your Next Property Decision With Clarity
If you’re asking whether you can get a Golden Visa with mortgaged property in the UAE, treat eligibility as part of a wider ownership decision. Consider how the property fits your investment goals, which records you’ll need to maintain, and whether your plans might involve refinancing, selling or changing ownership. This helps you assess a purchase beyond its immediate eligibility.
Before choosing a property, set your priorities: location, property type, ownership structure and long-term use. Then compare suitable options with the documentation and valuation requirements for your intended route. Upscale Real Estate Brokerage LLC can help you explore property opportunities as you make your decision.
Take the next step at your pace. Contact Upscale Real Estate Brokerage LLC to discuss your property plans and move forward with greater clarity.
Frequently Asked Questions
What are the benefits of having a UAE Golden Visa?
A UAE Golden Visa gives eligible property investors long-term residence without requiring a UAE national sponsor. The property investor permit is valid for 10 years and is renewable. In Dubai, holders are exempt from the 180-day absence rule. A visa holder may also sponsor a spouse and children for 10 years. These are residency benefits, not a route to citizenship; citizenship is separate from holding a residence permit.
What must a bank NOC for the Golden Visa contain?
A bank NOC should state that the bank does not object to issuing the residence permit and show the amount paid and remaining balance. Check that the letter identifies the relevant property and that its figures match the mortgage records. For example, if the balance has changed since the NOC was prepared, the documents may show different loan positions. Keep current bank evidence together for submission.
Can you get a UAE Golden Visa with a mortgaged property?
Yes. A mortgage does not automatically prevent a property from qualifying for the UAE real estate investor Golden Visa. The property must meet the applicable value and ownership criteria, and you must document the financing. For a Dubai bank-financed purchase, the residence application requires a bank NOC. A loan used for this route must come from a local bank determined by the competent local authority.
What is the UAE property value threshold for a 10-year Golden Visa?
The property investor route requires qualifying property worth at least AED 2 million. In Dubai, the threshold can be met through one qualifying property or multiple properties, subject to the ownership records and valuation evidence. For off-plan units, the properties must be purchased from local companies approved by the competent local authority. The relevant records must support the value used in the application.
Does the AED 2 million Golden Visa property threshold refer to purchase price or current value?
For a Dubai application, assess the property against its DLD-recorded or DLD-assessed value, rather than relying only on the original purchase price. The title deed must show a value of at least AED 2 million. If the property’s market value exceeds that amount but the deed does not reflect it, an official evaluation certificate is required to support the higher valuation.
Can a mortgaged property qualify if the paid-up equity is less than AED 2 million?
Yes, paid-up equity below AED 2 million does not by itself disqualify a mortgaged property. A February 2026 policy circular removed the previous requirement to pay at least AED 1 million or 50% of the property value upfront. The application still needs evidence of qualifying property value, ownership, and financing, including the relevant bank documentation for a mortgaged Dubai property.
What documents are required for a Golden Visa application using mortgaged property?
Prepare a passport valid for more than 6 months, the title deed or e-Certificate of Title, and mortgage evidence. For a bank-financed Dubai property, include a bank NOC stating no objection and showing the amount paid and remaining balance. Applicants must be inside the UAE for Dubai’s investor application. A spouse relying on shared ownership should also provide a certified marriage certificate, attested and translated into Arabic.
Can multiple properties or jointly owned property be used to meet the AED 2 million threshold?
Yes, an applicant may combine qualifying properties registered in their name to meet the AED 2 million threshold. With jointly owned property, the applicant’s individual share must itself be worth at least AED 2 million, unless spouses combine ownership with a certified marriage certificate. If spouses jointly own property worth less than AED 4 million, only one spouse is eligible to apply and may sponsor the other.